Medical Alert Systems and Medicare in 2026: What Original Medicare Won’t Pay and What Might
5 min read · Last updated August 19, 2026
- Original Medicare (Part A and Part B) does not cover medical alert systems because they don’t meet Medicare’s definition of durable medical equipment (DME).
- Some Medicare Advantage plans can cover a medical alert device as a Special Supplemental Benefit for the Chronically Ill (SSBCI), a category created by the Bipartisan Budget Act of 2018.
- Medicaid Home and Community-Based Services (HCBS) waivers cover personal emergency response systems (PERS) in many states, but eligibility and covered devices vary by state.
- Checking your Medicare Advantage plan’s Evidence of Coverage or calling your state Medicaid office before you buy is the step that actually determines whether you pay anything at all.
In this article
- Why Original Medicare says no
- Where Medicare Advantage can say yes
- Medicaid’s separate path
- How to find out what applies to you
- What seniors get wrong
- Frequently asked questions
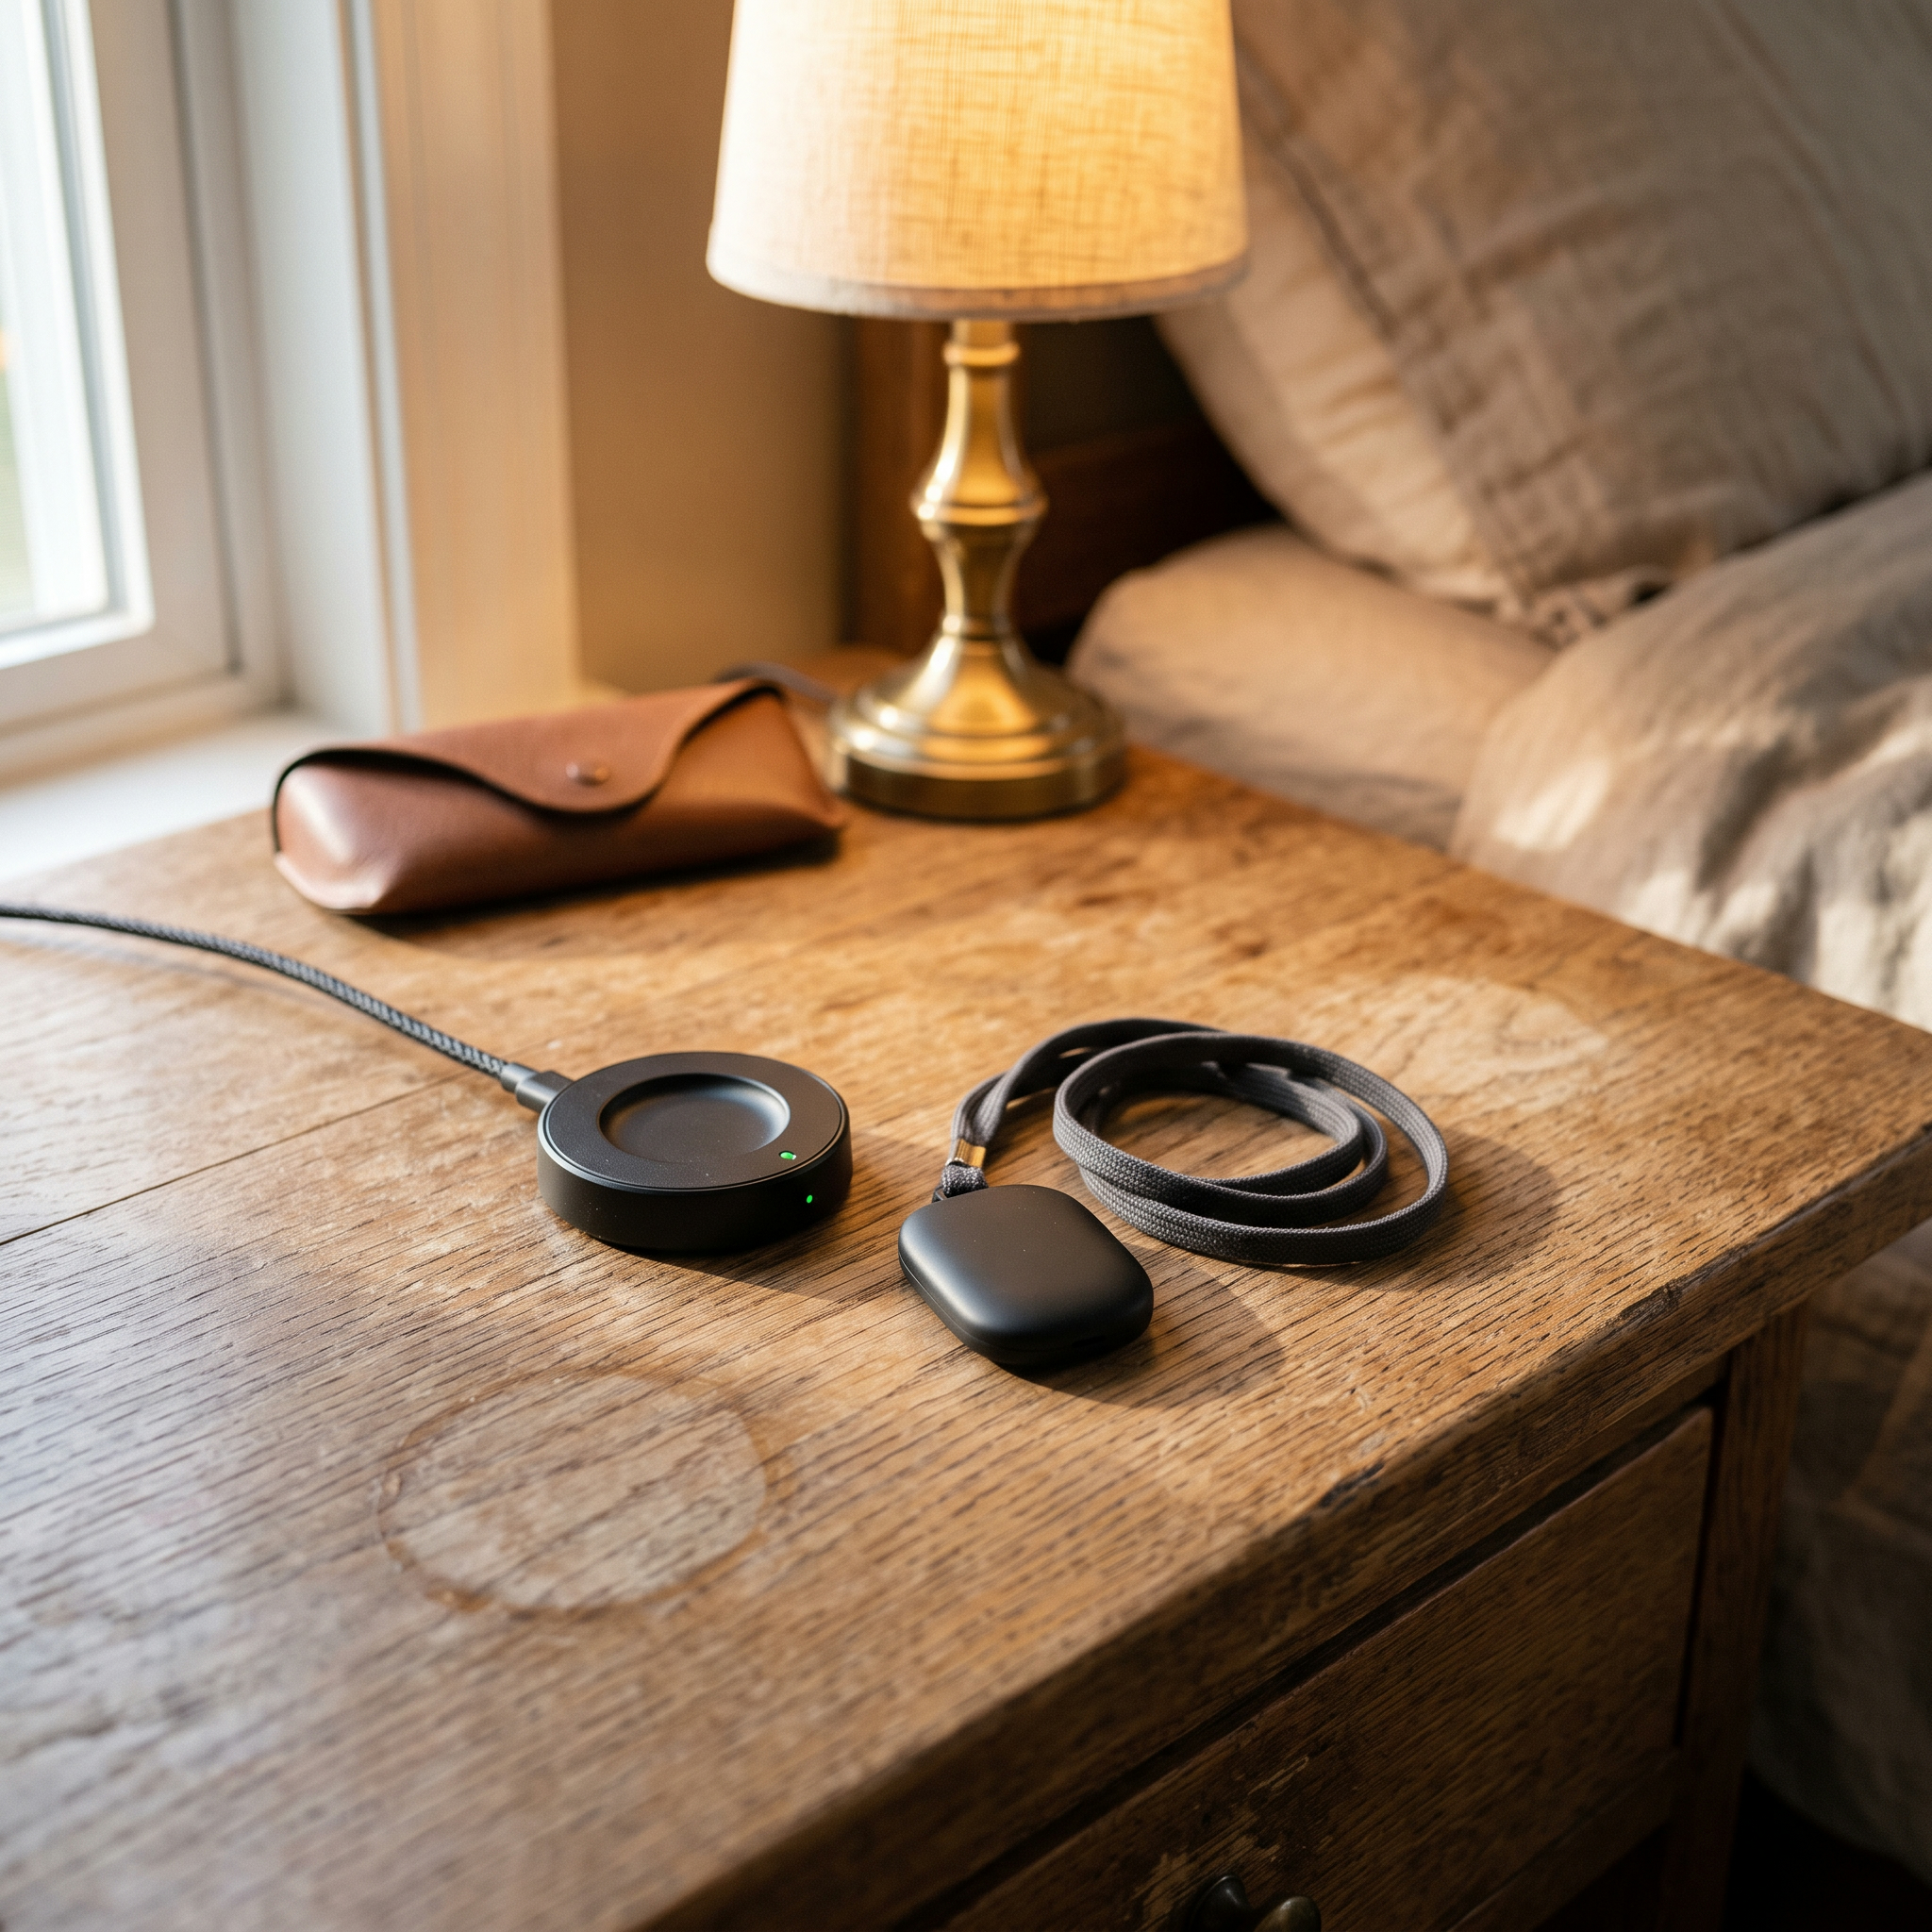
Frank, 74, fell in his bathroom in March and lay on the tile for 40 minutes before his neighbor happened to knock. His doctor’s office recommended a wearable alert button the same week. When Frank called to ask what Original Medicare would pay toward it, the answer surprised him: nothing, not a partial amount, not after a deductible. Zero.
Why Original Medicare says no
Medicare Part B pays 20% coinsurance on approved durable medical equipment (DME) after you meet the Part B deductible. But DME has a specific legal definition: it has to be durable, medically necessary, used for a medical reason, primarily useful to someone who’s sick or injured, and expected to last at least three years. Medicare’s own DME coverage page lists what qualifies, canes, walkers, wheelchairs, CPAP machines, hospital beds, and a medical alert system or personal emergency response system (PERS) isn’t on it.
The reasoning is narrower than it sounds. A PERS button doesn’t treat or monitor a medical condition the way a glucose monitor does. It’s a communication device, closer in Medicare’s eyes to a phone than to a wheelchair, even though its entire purpose is medical safety. That’s the boundary, and no amount of doctor’s-note paperwork moves it, because Original Medicare’s DME rule is fixed by regulation, not by medical necessity alone.
Where Medicare Advantage can say yes
Medicare Advantage (Part C) plans run under different rules. Since the Bipartisan Budget Act of 2018 created a category called Special Supplemental Benefits for the Chronically Ill (SSBCI), Medicare Advantage plans have had legal room to cover items that aren’t “primarily health related” at all, as long as the plan can show a reasonable expectation the item will improve or maintain a chronically ill enrollee’s health or overall function. The regulation itself spells out that standard.
A medical alert system fits that standard for someone managing a fall risk, a heart condition, or a chronic illness that could turn into an emergency. Some Medicare Advantage plans use SSBCI to cover a PERS device outright. Others don’t offer it at all. There’s no single national answer, because SSBCI benefits are optional and plan-specific. Whether yours covers it is written in your plan’s Evidence of Coverage document, not in a federal rule that applies to every enrollee.
| Coverage path | Who it applies to | What determines it |
|---|---|---|
| Original Medicare (Part A/B) | Everyone with Original Medicare | Never covers PERS, not classified as DME |
| Medicare Advantage (Part C) | Enrollees in a plan offering SSBCI | Plan-by-plan choice, check your Evidence of Coverage |
| Medicaid HCBS waiver | Medicaid-eligible seniors in a waiver program | State-by-state, varies by waiver |
| Private pay | Anyone not covered above | Monthly monitoring fee paid directly to the provider |
Medicaid’s separate path
If you have Medicaid, or you’re dual-eligible for Medicare and Medicaid, a third path opens up. Many states cover PERS devices through Medicaid Home and Community-Based Services (HCBS) waivers, the same waiver programs that fund in-home aides and adult day services to help people stay out of a nursing facility. Coverage isn’t automatic just because your state has an HCBS waiver; it depends on which waiver you’re enrolled in and what that specific waiver’s service list includes.
This is also where a caregiver researching on a parent’s behalf tends to get stuck: state Medicaid offices don’t publish a single national list of what each waiver covers. The Eldercare Locator, a public service of the federal Administration for Community Living, connects callers to their local Area Agency on Aging, which can tell you which waiver programs operate in your county and whether PERS is on the list.
How to find out what applies to you
Three calls settle this, in order. First, if you have a Medicare Advantage plan, call the member services number on your card and ask specifically whether your plan covers a personal emergency response system as a supplemental benefit, not just whether it covers “medical alert systems” in general, since the SSBCI framing is what triggers the right answer. Second, if you have Medicaid or think you might qualify, call your state Medicaid office or your local Area Agency on Aging and ask which HCBS waivers you’re eligible for and whether PERS is a covered service under them. Third, if neither applies, ask the medical alert provider directly for their monthly self-pay rate before you sign anything, since rates and contract lengths vary by company.
If you’re weighing an alert system against bigger home-safety changes, see our guide to home modification grants and loans for aging in place, since the two often come up in the same conversation with an Area Agency on Aging.
What seniors get wrong
The most common mistake is asking the wrong question. “Does Medicare cover medical alert systems?” gets a flat no from Original Medicare and stops the search there. The right question is “does my specific plan or my state’s Medicaid waiver cover it?” because that’s where the actual answer lives. The second mistake is signing a medical alert contract before making either call, locking in a monthly fee that a Medicare Advantage or Medicaid benefit might have covered at no cost.
Program details and coverage rules change. Verify your plan’s current Evidence of Coverage or contact your state Medicaid office before assuming any coverage applies to your situation.
A daily wellness check does not have to come from a device alone. Home-delivered meals under the Older Americans Act build a similar daily check-in into every delivery, with no federal income test required.
Frequently asked questions
Does Original Medicare cover medical alert systems at all, even partially? No. Original Medicare Part A and Part B do not cover medical alert systems or personal emergency response systems under any circumstance, because they aren’t classified as durable medical equipment. There’s no partial coinsurance option the way there is for a wheelchair or CPAP machine.
How do I find out if my Medicare Advantage plan covers one? Call the member services number on your plan card and ask whether your plan offers a Special Supplemental Benefit for the Chronically Ill that includes a personal emergency response system. Your plan’s Evidence of Coverage document, mailed annually, also lists supplemental benefits by name.
Will Medicaid pay for a medical alert system if I qualify? Possibly, through a Home and Community-Based Services waiver, but it depends on your state and which specific waiver you’re enrolled in. Contact your state Medicaid office or local Area Agency on Aging to check.
What if none of these apply to me? You’d pay the provider’s monthly monitoring fee directly. Ask for the exact rate and contract terms in writing before signing, and compare more than one provider since rates vary.
Can I switch to a Medicare Advantage plan just to get this benefit? You can only enroll in or switch Medicare Advantage plans during specific enrollment windows, and SSBCI benefits vary by plan and change year to year, so confirm the specific benefit is included before switching for that reason alone.